The FDIC also supervises certain financial institutions and participates in resolving failed banks. Its deposit insurance program is funded through assessments paid by insured financial institutions rather than ordinary consumers purchasing individual insurance policies.
The Federal Deposit Insurance Corporation is an independent agency of the United States government established to maintain confidence in the banking system. Its primary responsibility is protecting depositors when an insured bank fails.
FDIC insurance is automatic for eligible deposits held at an insured bank. Customers do not need to submit a separate application, pay an insurance premium, or register their accounts.
The protection applies to qualifying deposits regardless of whether a customer has a small checking account or substantial savings. However, the amount protected depends on account ownership, the financial institution, and applicable insurance rules.
How Does FDIC Insurance Work?
FDIC insurance protects eligible bank deposits if an insured financial institution closes because it cannot meet its financial obligations.
When a bank fails, the FDIC generally takes responsibility for resolving the situation. One possible approach is arranging for another insured bank to acquire the failed institution. In that situation, customers may gain access to their deposits through the acquiring bank.
If another bank does not assume the deposits, the FDIC can pay insured depositors directly. It determines the amount each customer is entitled to receive based on account records and applicable coverage limits.
The FDIC maintains a Deposit Insurance Fund to support its insurance and bank-resolution responsibilities. Insured banks pay assessments into this fund, which helps finance deposit protection and related resolution activities.
Importantly, FDIC insurance is backed by the full faith and credit of the United States government. It is designed to protect depositors against insured bank failures, not ordinary investment losses or every financial problem a consumer might experience.
What happens when an insured bank fails?
The process generally involves several steps:
- Banking regulators close the failing institution.
- The FDIC is appointed to manage the resolution.
- The FDIC determines how deposits will be handled.
- Insured customers receive access to their covered funds through an acquiring institution or an insurance payment process.
- Claims involving deposits above insurance limits may be handled separately as part of the failed bank’s receivership.
The exact resolution process depends on the circumstances of the bank failure. However, the primary purpose is to protect insured depositors and maintain confidence in the banking system.
What Is the FDIC Insurance Coverage Limit?
One of the most important features of FDIC insurance is its standard coverage limit.
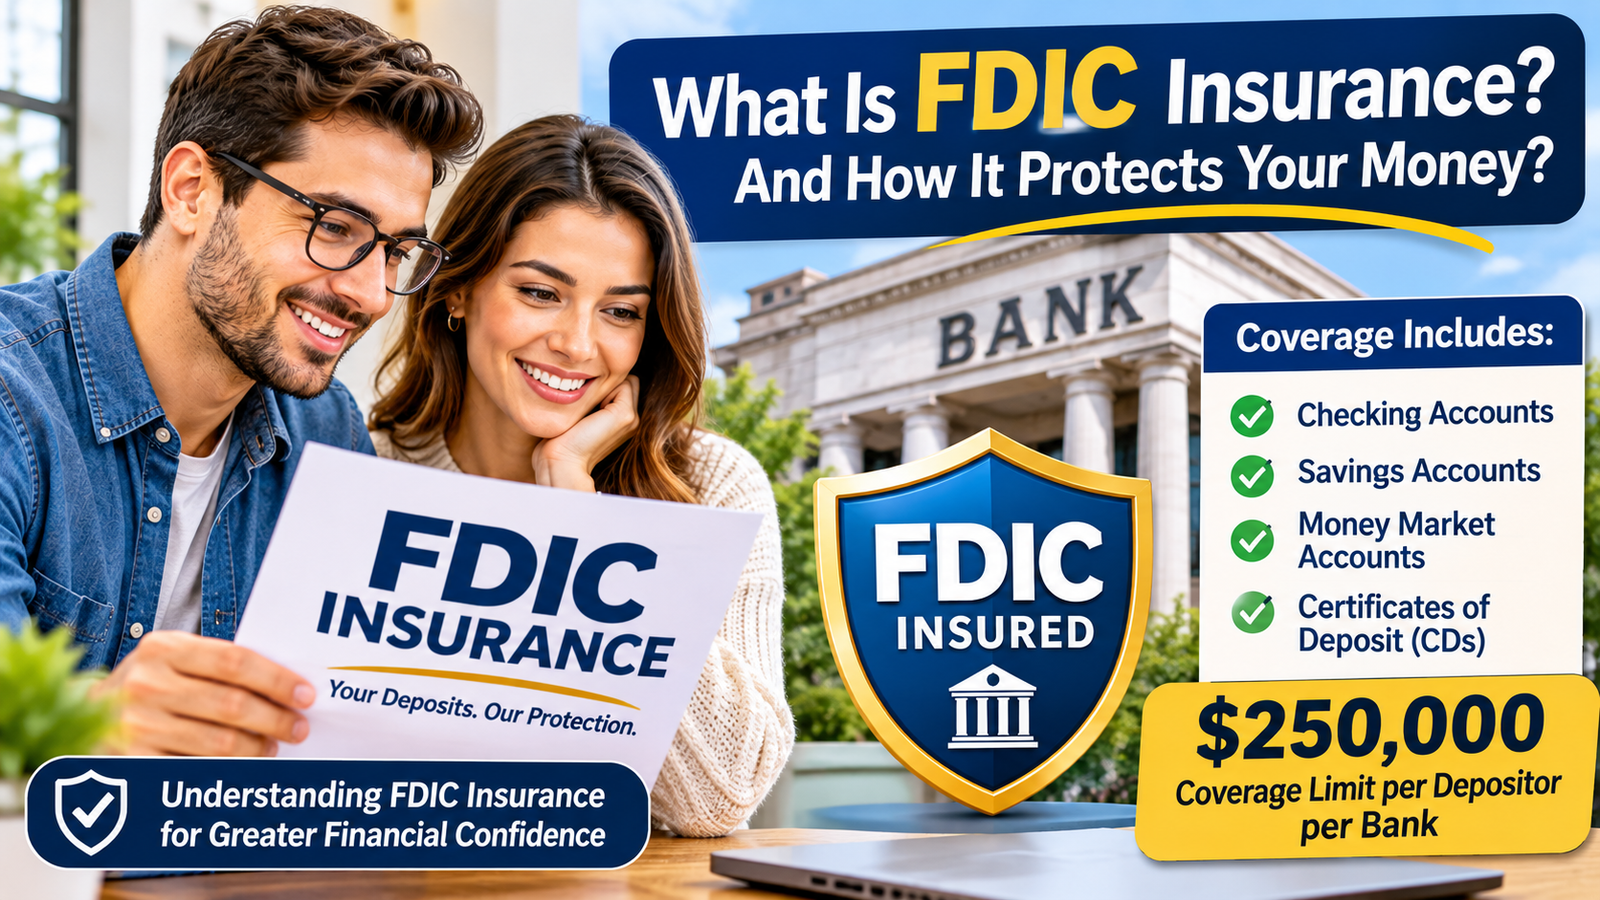
The standard maximum coverage is $250,000 per depositor, per FDIC-insured bank, per ownership category.
This means the limit does not simply apply to each individual account. Instead, the FDIC considers how deposits are owned and groups eligible accounts accordingly.
For example, someone who has a checking account and a savings account in the same ownership category at the same bank generally has those balances combined when calculating insurance coverage.
Different ownership categories may qualify for separate coverage at the same insured institution, provided all applicable requirements are satisfied.
Understanding account ownership categories
The FDIC recognizes several ownership categories, including:
- Single accounts: Deposits owned by one person without beneficiaries.
- Joint accounts: Deposits owned by two or more people who meet the applicable ownership requirements.
- Certain retirement accounts: Eligible deposits held in qualifying retirement accounts, including traditional and Roth IRAs.
- Trust accounts: Eligible deposits held under qualifying revocable or irrevocable trust arrangements.
- Business accounts: Qualifying deposits owned by corporations, partnerships, and certain other business entities.
- Government accounts: Deposits held by qualifying government entities.
Each category has specific requirements. Simply opening multiple accounts or adding another person’s name does not automatically create additional insurance coverage.
Hypothetical Example 1: Multiple Accounts at One Bank
Imagine someone has the following deposits at the same FDIC-insured bank:
- Checking account: $80,000
- Savings account: $90,000
- Certificate of deposit: $60,000
All three accounts belong to the same individual in the same ownership category.
The combined balance is $230,000. Because this amount is below the standard $250,000 coverage limit, the entire eligible balance would generally be insured.
The example illustrates why the FDIC combines qualifying deposits rather than calculating coverage separately for every account.
Hypothetical Example 2: Deposits at Two Different Banks
Imagine another individual has $200,000 in eligible savings deposits at Bank A and $200,000 in eligible savings deposits at Bank B.
Both institutions are separately chartered FDIC-insured banks, and the accounts belong to the same ownership category.
The standard insurance limit applies separately at each bank. Therefore, the eligible deposits would generally be covered at both institutions.
This example demonstrates that the FDIC calculates coverage based on the insured banking institution and ownership category, not simply the total amount of money someone holds across the entire banking system.
These examples are hypothetical and do not replace an individual insurance coverage calculation.
Which Bank Accounts Are Covered by FDIC Insurance?
FDIC insurance generally covers eligible deposit products held at participating insured banks.
Common examples include:
- Checking accounts: Used for everyday financial transactions, including deposits, withdrawals, and bill payments.
- Savings accounts: Designed for holding money while maintaining access to deposited funds.
- Money market deposit accounts: Bank deposit accounts that may combine savings features with certain transaction privileges.
- Certificates of deposit (CDs): Time deposits that generally require money to remain deposited for an agreed period.
- Certain official bank instruments: Qualifying cashier’s checks and money orders issued by insured banks.
Coverage is generally automatic when an eligible deposit is placed at an FDIC-insured institution.
However, customers should distinguish between a bank deposit account and an investment product that happens to be offered through a bank.
The institution’s insured status and the legal nature of the product both matter.
For example, a bank may provide access to savings accounts and investment services through the same location. The savings account may qualify for FDIC insurance, while securities purchased through the investment service do not.
What Does FDIC Insurance Not Cover?
FDIC insurance has important limitations. It protects eligible deposits against insured bank failures, but it does not guarantee the value of every financial product.
The following products are generally not covered by FDIC deposit insurance:
- Stocks and exchange-traded securities.
- Corporate and municipal bonds.
- Mutual funds, including money market mutual funds.
- Annuities.
- Life insurance policies.
- Cryptocurrency and other crypto assets.
- U.S. Treasury bills, notes, and bonds.
- Safe deposit boxes and their contents.
These products may involve different types of legal protections or financial risks, but they are not insured bank deposits.
An important distinction exists between a money market deposit account and a money market mutual fund. The former is a bank deposit that can qualify for FDIC coverage. The latter is an investment product and is not protected by FDIC deposit insurance.
FDIC insurance also does not protect consumers against ordinary losses resulting from fraud, identity theft, unauthorized transactions, or disputes with financial institutions. Other consumer protection laws and procedures may apply to those situations.
Similarly, FDIC insurance does not guarantee that a nonbank financial technology company will meet its obligations to customers. Even if such a company works with an insured bank, the arrangement and legal ownership of the funds matter.
How to Check Whether Your Bank and Deposits Are Insured
Consumers can verify whether a financial institution participates in the FDIC insurance program using the FDIC’s official resources.
The FDIC provides a BankFind tool that allows users to search for insured financial institutions.
When checking a bank, consider the following:
- Verify the institution: Confirm that the actual bank holding the deposits is FDIC-insured.
- Identify the account type: Determine whether the financial product is an eligible deposit account.
- Review account ownership: Check whether accounts are classified as individual, joint, retirement, trust, or another ownership category.
- Combine relevant balances: Include all deposits belonging to the same ownership category at the same bank.
- Review the coverage limit: Compare the combined eligible deposits with the applicable insurance amount.
The FDIC also provides an Electronic Deposit Insurance Estimator, commonly known as EDIE. This resource helps consumers estimate their coverage based on account balances and ownership arrangements.
For complicated situations involving trusts, business accounts, retirement accounts, or deposits held through intermediaries, the applicable rules may require additional attention.
Consumers should also remember that separate branches of the same insured bank do not receive separate insurance limits simply because they operate at different physical locations.
Why Is FDIC Insurance Important for the U.S. Banking System?
FDIC insurance plays an important role in maintaining confidence in the American banking system.
Before federal deposit insurance existed, bank failures could cause depositors to lose access to their savings. Concerns about financial institutions could also encourage customers to withdraw money rapidly, creating additional pressure on banks.
Federal deposit insurance was established to reduce these risks and strengthen public confidence in banks.
Its importance extends beyond individual account holders.
Protecting household savings
Many households keep money in checking and savings accounts to manage everyday expenses, pay bills, and maintain financial reserves.
Deposit insurance helps protect eligible balances when an insured bank fails, reducing the potential financial disruption for covered depositors.
Supporting financial stability
When people understand that eligible deposits are protected within established limits, they may have greater confidence in keeping money within the regulated banking system.
This can help reduce the risk that concerns about one institution will trigger unnecessary withdrawals from other banks.
Supporting access to banking services
Deposit insurance also contributes to confidence in ordinary banking services, including savings accounts, checking accounts, and certificates of deposit.
Nevertheless, it does not eliminate all banking risks. Institutions can still fail, consumers can experience service disruptions, and uninsured balances may be subject to additional recovery procedures.
Understanding both the benefits and limitations of FDIC insurance provides a more realistic picture of how the protection works.
Key Takeaways
- FDIC insurance protects eligible deposits when an insured U.S. bank fails.
- The standard coverage limit is $250,000 per depositor, per insured bank, per ownership category.
- Checking accounts, savings accounts, qualifying money market deposit accounts, and CDs are generally covered.
- Stocks, bonds, mutual funds, annuities, and cryptocurrency are not covered by FDIC deposit insurance.
- Coverage is automatic for eligible deposits, but consumers should verify the bank, account type, and ownership arrangement.
Frequently Asked Questions About FDIC Insurance
1. Is FDIC insurance free?
Yes. Consumers do not pay a separate premium or enrollment fee for FDIC deposit insurance. Coverage is automatic for eligible deposits held at an insured bank. Financial institutions fund the insurance system through assessments paid into the FDIC’s Deposit Insurance Fund.
2. Does FDIC insurance cover more than $250,000?
It can. The standard limit applies separately to qualifying ownership categories at each insured bank. For example, eligible single and joint accounts may receive separate coverage. However, additional coverage depends on account ownership, proper documentation, and the FDIC’s applicable requirements.
3. Are online bank accounts FDIC-insured?
Online bank accounts can qualify for FDIC insurance if the deposits are actually held at an FDIC-insured bank. The fact that an account is available through a website or mobile application does not establish coverage. Consumers should identify the underlying bank and verify its insured status.
4. Does FDIC insurance cover retirement accounts?
Certain retirement deposits, including eligible traditional and Roth IRA deposits, receive separate coverage under the retirement account ownership category. However, this protection applies to eligible bank deposits, not every investment held inside a retirement account. Stocks, bonds, and mutual funds are not FDIC-insured.
5. How quickly does the FDIC return money after a bank failure?
The FDIC generally works to provide insured depositors with prompt access to their covered funds. In many bank failures, another insured institution assumes the deposits, allowing customers to access their money through that institution. The exact timing and process depend on how the failed bank is resolved.
Conclusion
FDIC insurance is an important part of the U.S. financial system because it protects eligible bank deposits when an insured institution fails. Understanding the coverage limit, account ownership categories, and types of protected deposits helps consumers distinguish insured savings from financial products that carry investment risk. Although FDIC insurance provides meaningful protection, it does not cover every financial loss or guarantee every product offered by a bank. Knowing how FDIC insurance works allows individuals to better understand their deposit protection and the role federal insurance plays in maintaining confidence in American banking.
Sources and Further Reading
The following official U.S. resources provide additional information about deposit insurance and consumer financial protection:
- Federal Deposit Insurance Corporation (FDIC): Deposit Insurance
- FDIC: Understanding Deposit Insurance
- FDIC: Your Insured Deposits
- FDIC: Deposit Insurance FAQs
- FDIC: BankFind Suite
Disclaimer
Disclaimer: This article is for educational purposes only and is not financial, investment, tax, or legal advice. The information provided is general in nature and does not consider your personal circumstances. We make no guarantees, promises, or representations about returns, profits, savings, credit outcomes, or any other results. All examples are hypothetical and for illustration only. Financial rules, interest rates, tax brackets, contribution limits, and fees change over time, so this article does not state current figures; please check official sources such as IRS.gov, SEC.gov, Investor.gov, CFPB, or the Federal Reserve for the latest information. Consult a qualified professional, such as a certified financial planner, tax professional, or attorney, before making financial decisions.
About the Author: [Author Name] is [credentials/experience in finance, writing, or research]. [One or two sentences about expertise.]